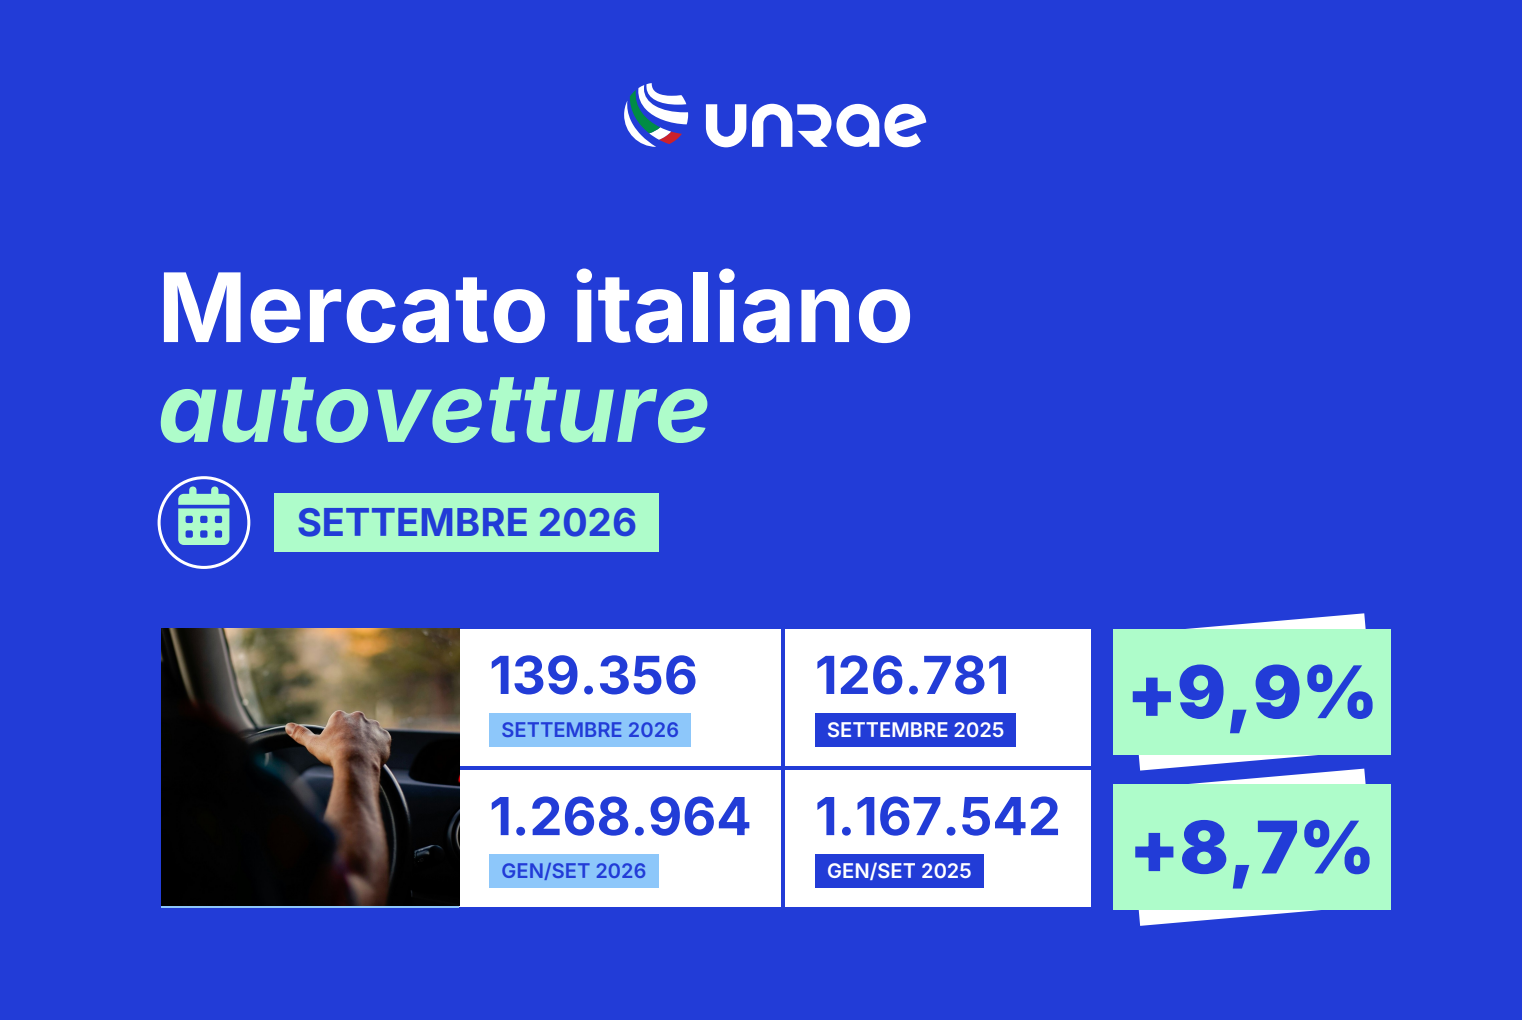
ROMA (ITALPRESS) – In September the motor vehicle sector returns to express a more sustained growth, recording a +9.9% with 139.356 new registrations, in front of the 126.781 units listed in September 2025. The consumption of the first nine months of the year shows an increase of 8.7%, reaching 1,268.964 registrations regarding 1.167.542 of the corresponding period 2025. However, comparison with 2019 still maintains a significant gap, with a contraction of 13.6%, to prove how current levels still do not allow to talk about normalization of volumes.
As regards power supplies, in September the electric cars as well (BEV) recorded a share of 7.6%, recovering from 6.4% of August and growing on 5.6% of September 2025. More than 52% of BEV volumes are concentrated in the private customer segment, with a presence of the corporate channel that would certainly be stronger if it was finally accompanied by an appropriate tax regime. The plug-in hybrids (PHEV) consolidate their position of importance by placing at 11.1% of the share – just below 12.0% of August 2026 and above 8.5% of September 2025 – driven by long-term rental that originates over 40% of the channel registrations.
“The renewal of the circular park must remain a strategic priority. The positive signals of the new market are important, but read together with the data of the use – where about half of the net transfers concerns cars with over ten years – show clearly that the real challenge is to activate mechanisms capable of transforming the resumption of registrations into a progressive ageing of the park. This is where the real impact on safety, efficiency and sustainability of mobility is measured,” says Roberto Pietrantonio, President of UNRAE.
On the side of energy policies, the main operators of the fuel distribution introduced provisional roofs to the petrol and oil lists until the end of October. UNRAE welcomes these measures to protect the purchasing power of families and businesses, but highlights how cost reduction should be integrated into an organic design. Structural interventions are needed that are not limited to lowering the final price of fuel, but reduce the country’s energy dependence and its exposure to international crises, favoring the renewal of the circulating park and the energy transition, with access to more efficient vehicles, zero and low emissions.
In parallel, the D.L. Support for the examination of the Parliament allocates 2.3 billion euros to the compensatory transfers for the exemption from the auto stamp in 2027 (with the contest of 1.460 million PNRR economies): the threshold of 80 kW, free from emissive parameters and old age, calls for a remodelling of the intervention in the key of decarbonization and road safety.
“We welcome the temporary lightening of the draft introduced by the Government, but we ask that the overall economic commitment be linked to a vision capable of stimulating the replacement of the most obsolete models: the constructive confrontation with the chain is indispensable to accelerate the adoption of efficient and safe solutions with structural effects beyond 2027,” continues Pietrantonio. Finally, in view of the Budget Law, UNRAE reiterates the centrality of the defiscalization plan for business fleets, from the estimated cost in 515 million euros in the three years 2027-2029, to activate 400,000 sustainable registrations. “The next budgetary manoeuvre is an unmissable step to finally define a certain regulatory framework to support corporate investment. This is why we reaffirm the need to launch from 2027 the proposal for a supply chain with guaranteed resources on the whole three years, intervening on three main axes: an organic revision of the taxation of corporate cars aligned with European parameters, a capillary strengthening of charging infrastructure and an effective reduction of energy costs, so as to feed a market of the recent and accessible use for families”, concludes President Pietrantonio.
The analysis of the structure of the market of the month, in the profile of the users shows in September a good growth dynamic for the individuals who confirm the 55.9% share (+0.1 p.p.) and close the 9 months to 53.6% share (+0.8 p.p.). Also autoimmatricolazioni in September grow in volume and quota, at 13.9% share (+0.2 p.p.), at 11.3% in January- September (-0.3 p.p.). A slight increase involves long-term rental which yields 1,4 points of share, to 21,5% of the total (21.1% in the first 9 months, -2,2 p.p.), for the growth of Top companies, in the face of a decline of Captives. A very strong acceleration affects short-term rental, which almost doubles volumes, to 2.9% share (+1.2 p.p.); in January-September the share rises to 8.7% (+2.1 p.p.). Although with growing volumes, companies in the month stop at 5.7% of share (-0.2 p.p., 5.3% in cumulation).
Between the power supply, in September the gasoline engine loses 4.8 points and drops to 17,6% of altitude (19.4% in the piled, -5.8 p.p.). The diesel retrocede in last position between the engines, yields 4 points of share in the month, stopping at 4.9% in September and 6.5% in the 9 months. The Gpl in the month drops to 8.1% (-1.2 p.p.), and to 7.1% in January-September (-2.2 p.p.). The hybrids, market leader, in the month recover well 5.5 points, exceeding half of the registrations, to 50.7% share (49.4% in the first 9 months), with an 18.5% for the “full” hybrid and 32.2% for the “mild” hybrid. The cars BEV, as anticipated, close the month of June to 7.6% share, 2 points in more than 2025 (8.0% in the cumulation); the PHEV climbed to 11.1% compared to 8.5% a year ago (9.5% in January-September, +3.5 p.p.).
Segmentation analysis shows in September a good growth in segment A berlin volumes, at 9.9% of the total, in the face of a contraction of SUVs, at 1.5% share. In more dynamic growth, segment B berlines at 16.2%, while the Suvs – with a slight increase in volume, fall to 28.6%. In the medium-sized segment (C) the berline decreases, to 3.9% of the share, while the Suv earn 3.7 points, to 23.6%. Segment D caps rise to 1.2%, and the Suv to 9.2% of the total. At the top of the range both the berline and the Suv, respectively 0.1% and 1.2% share. Finally, the wagon stations represent 2.1% of the total, MPV 1.9% and sports 0.5%.
On the geographical front, in September the North West confirms the first position and recovers 1,5 points of altitude, going up to 32.7%, while the Center earns 1,1 points with 28.7% of total registrations, however thanks to the rental, without which it would lose more than 6 points, stopping at 22.6%. The North East loses 4 points, at 22.2% (22.9% net of rental); the South rises at 10.5% (+0.6 p.p.) and the Islands at 5.8% (+0.6 p.p.).
The average CO2 emissions of new registrations in September lose 3.7% and fall to 106.0 g/Km; in the first 9 months they fluctuate 5.8%, to 107.2 g/Km. The analysis of the registrations by CO2 range reflects the trend in September of cars BEV and PHEV: the ZEV range (0 g/Km) represents 7.6% of the market, 0.2% the 1-20 g/Km band (respectively 8.0% and 0.8% in 9 months). The 21-50 g/Km range weighs 5.9% of the total and 51-60 g/Km 2.8% (in the first 9 months respectively 4.8% and 2.0%). The 61-94 g/Km represents 4.6% (4.9% in cumulation), 95-135 g/Km 62.5% (60.6% in January-September), while the share of cars from 136 to 190 g/Km leads to 12.9% and that of the band more than 190 g/Km at 1.6% (respectively 15.2% and 1.6% in cumulated).
– photo office press Unrae –
(ITALPRESS).
